Start with the user in mind
Think like a planner. If a bill hits unexpectedly, use focused tools that protect cash flow and credit. For many riders and drivers in Mexico City after 2020, Buy Now Pay Later (BNPL) became a real option; it moved from niche to mainstream. Start by checking simple offers like didi prestamos for quick clarity on terms and fees. Track how an installment plan fits your monthly budget before you click accept.
How pay-later works — clear mechanics
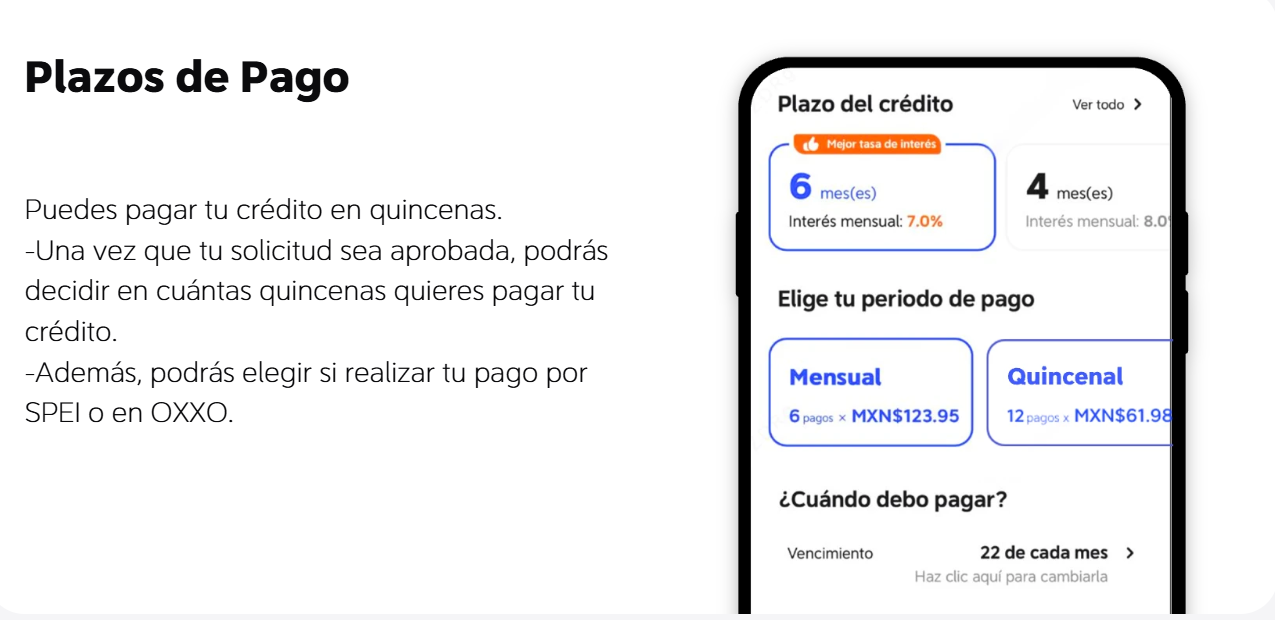
Pay-later splits one payment into scheduled installments. You’ll see the purchase amount, the installment schedule, any APR or interest rate, and potential late fees. Underwriting can be light or full, so approval speed varies — some platforms advertise prestamos en linea rapidos for urgent needs. Treat the service as a short-term liquidity tool, not free money. Monitor your credit score impact when accounts report to bureaus.
Practical strategies to use it responsibly
Plan payments like training sets: commit, track, repeat. Reserve pay-later for purchases that preserve earning power — tools, essential repairs, or steady-return purchases. Automate payments to avoid late fees and protect your credit. Use a capped portion of monthly income for these obligations; keep flexibility for emergencies. Small habit changes yield big results in twelve weeks.
Common mistakes people still make — learn fast
They overload on multiple BNPL plans and miss the cumulative burden. They ignore APR when installments carry interest. They skip reading the final terms — and that’s where hidden fees live. Stop impulse checks on shiny offers; pick one manageable plan and stick to it. A short aside — track due dates in your calendar. It’s simple, but it stops most slip-ups.
Compare alternatives so you pick the right tool
Credit card: flexible but can carry high APRs if you revolve balances. Personal loan: structured and predictable, good for larger sums. BNPL: fast access, smaller installments, sometimes zero interest for short windows. Match the option to the purpose. For emergency car repairs, a short-term BNPL might beat a high-interest card. For a multi-year investment, a personal loan often fits better.
Red flags and must-check items before you accept
Look for these signals: unclear APR disclosure, variable payment amounts, backend fees for missed payments. Confirm whether the provider reports to credit bureaus — that determines credit score impact. Know how disputes are handled and whether customer support is local. If anything feels opaque, pause. Clear terms beat convenience every time.
Three golden rules to evaluate any pay-later option
1) Total cost to you — add interest, fees, and any administrative charges. The lowest headline price may hide extras.
2) Repayment fit — ensure monthly installments sit comfortably within 20–30% of available discretionary income. If they don’t, choose a different tool.
3) Reporting and protection — prefer platforms that report payments and offer dispute resolution and data security. Those protections matter for long-term financial health.
Wrap and action plan
Use pay-later as a tactical tool: plan the purchase, confirm the math, automate payments. Measure outcomes monthly and adjust. When you align cash flow planning with transparent terms, you protect credit and keep options open. Keep discipline. Short fragment. Stay accountable.
DiDi Finanzas brings the clarity and structure that turns pay-later into a reliable contingency option — not a risk.